City limitsPlace boundary
Curated city comparison

FargoColumbia

Midwestern regional centers with similar population scale and materially different gross-yield, renter-pressure, housing-stock and local-demand evidence.

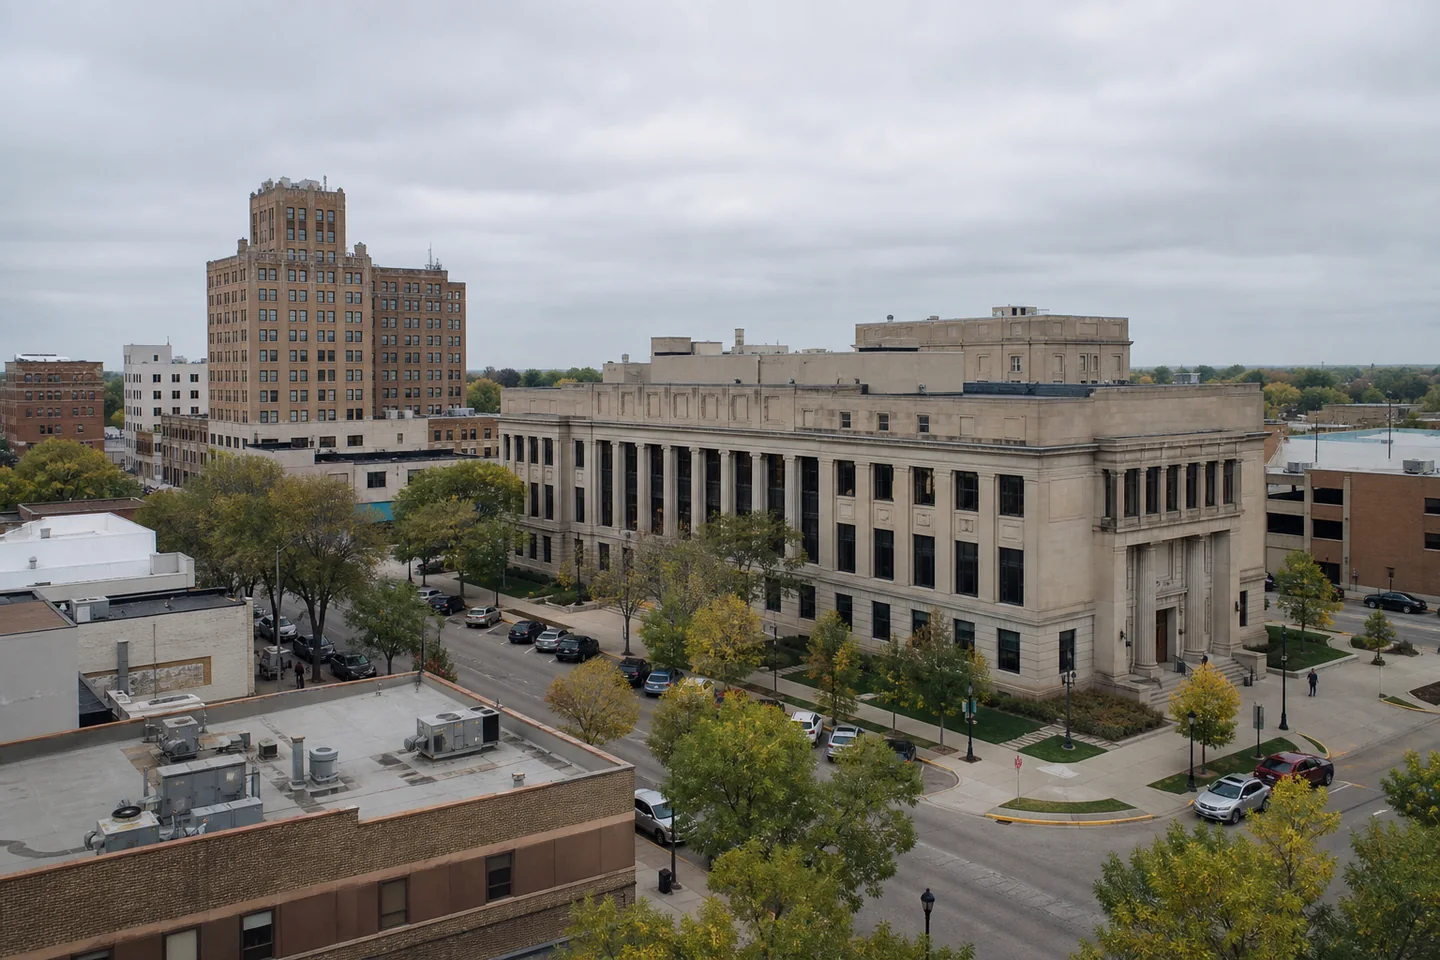
Fargo, ND cityscape
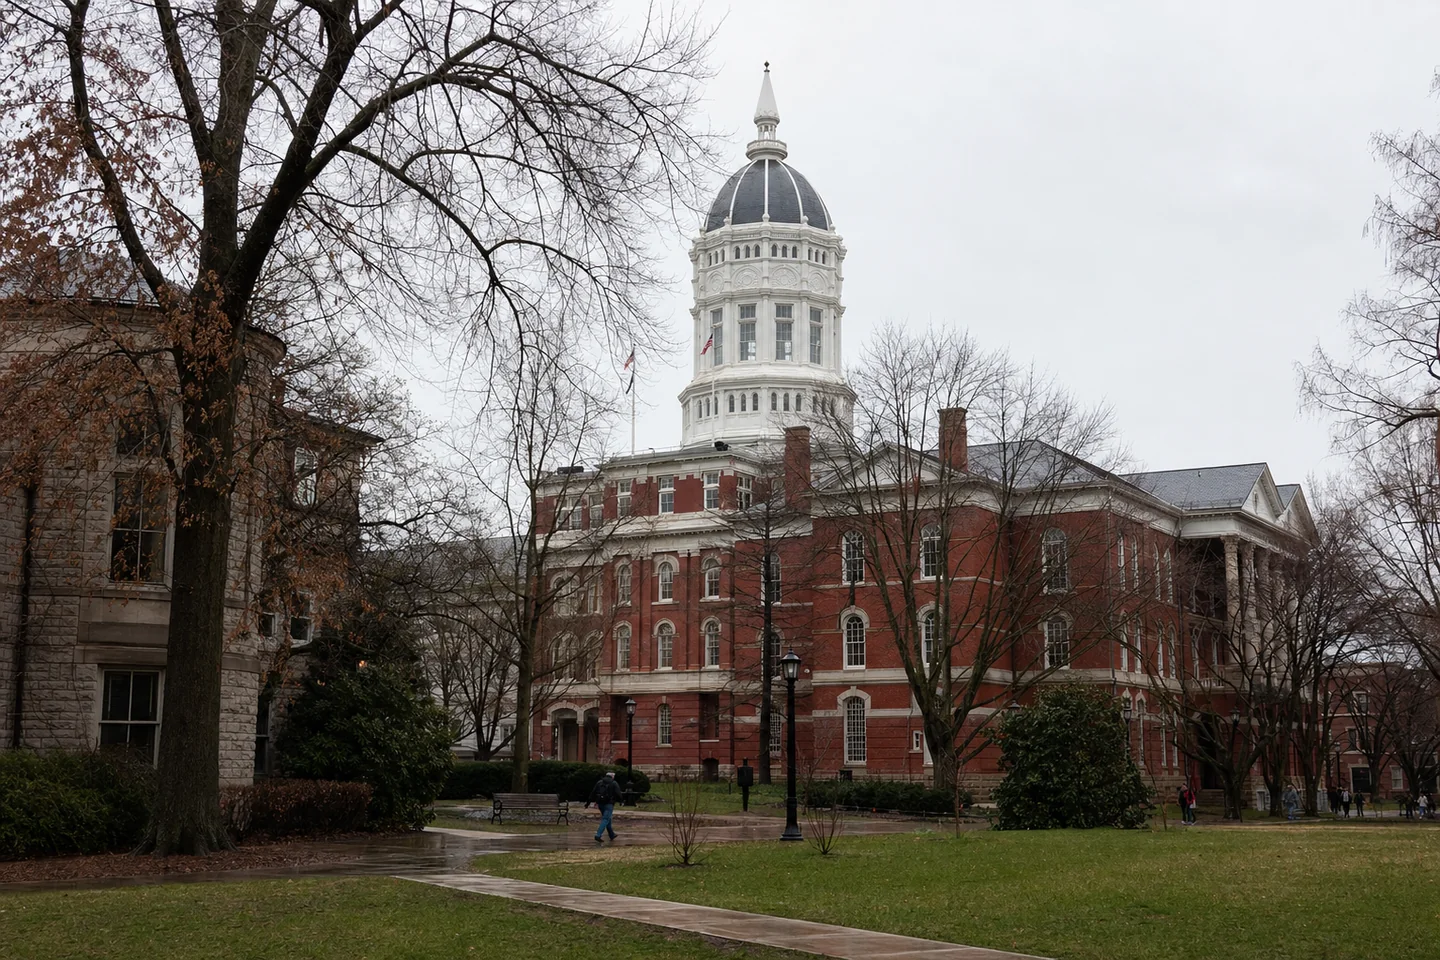
Columbia, MO cityscape
Decision memo

The trade-off before property underwriting

The interpretation uses direct city records only. County and metro averages are not substituted into this comparison.

Columbia, MO better fits cash_flow: its 5.17% gross yield exceeds Fargo, ND’s 4.02%, supported by a higher Zillow rent index despite a higher Zillow value. That spread is only a screening signal because gross yield excludes every major operating and capital cost. Underwriting should next test achievable unit rent, vacancy, concessions, taxes, insurance, repairs, management and financing.

Fargo better fits entry_affordability and housing_stock. Its Zillow value is $324,918 versus Columbia’s $330,373, while price to household income is 4.85 versus 4.97. Fargo also offers a much larger large-multifamily share, 37.04% against 10.75%, whereas Columbia is more single-family-oriented. Investors should verify whether Fargo’s broader multifamily inventory creates acquisition choice or stronger competing supply at the specific submarket and property level.

Renter_pressure depends on strategy. Fargo has the larger renter share and slightly lower vacancy, but Columbia’s 50.96% rent-burden share is not clean upside: it may indicate demand pressure while also constraining collections and further rent growth. Fargo better fits local_demand because population change was 7.99% versus 6.04%, poverty and unemployment were lower, and household income was slightly higher. Population change compares overlapping ACS vintages and is not annualized.

Direct city matrix

The same definition on both sides

“n/a” remains missing. Zillow indexes and ACS survey measures stay visibly separate.

Decision evidenceFargo, NDColumbia, MO
Typical home valueZillow ZHVI · city$324,918$330,373
Observed market rentZillow ZORI · city$1,088$1,424
Gross yieldZORI × 12 ÷ ZHVI · before costs4.0%5.2%
Price to household incomeZillow value ÷ ACS income4.85x4.97x
Annual rent to incomeZillow rent × 12 ÷ ACS income19.5%25.7%
Rent burdenACS renter households paying 30%+40.5%51.0%
Renter shareACS occupied housing56.3%51.3%
Vacancy rateACS all housing units6.0%6.2%
Population changebetween ACS vintages · not annualized▲ 8.0%▲ 6.0%
UnemploymentACS civilian labor force3.8%4.0%
Entry and income screen

Price, rent and yield do not tell the same story

Bars begin at zero within each measure. Gross yield remains a before-cost screen.

FargoColumbiaTypical home valueZillow ZHVI · city$325k$330kObserved market rentZillow ZORI · monthly city index$1k$1kGross yieldZORI × 12 ÷ ZHVI · before costs4.0%5.2%
Zillow city ZHVI and ZORI · 2026-06 / 2026-06
Price and rent history

Two city paths, each rebased to 100

Each panel keeps price and rent in its own city; no level is borrowed across geographies.

Five-year path

Price and rent, rebased to 100

ZHVI +23.6%ZORI +24.1%
12411095202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Five-year path

Price and rent, rebased to 100

ZHVI +32.6%ZORI +47.7%
14812195202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Fit by objective

There is no universal city winner

Five city questions remain separate so a yield lead cannot erase affordability or demand risk.

01
Cash-flow screenColumbia

Columbia, MO better fits cash_flow at the screening stage: its gross yield is 5.17% versus 4.02% in Fargo, ND, while its Zillow rent index is $1,424 versus $1,088. Do not treat that as net return. The next check is a property-level operating statement covering vacancy, concessions, management, repairs, taxes, insurance, utilities, financing and capital work, all of which are excluded from gross yield.

02
Entry affordabilityFargo

Fargo, ND better fits entry_affordability, though narrowly. Its Zillow city value index is $324,918 versus $330,373 in Columbia, MO, and its price-to-income measure is 4.85 versus 4.97. These city indexes establish a relative entry screen, not a quote for any building. Underwriting should next compare actual asking prices, unit count, condition, deferred maintenance and rentable area for matched properties in each city.

03
Renter pressureDepends on the property

Renter_pressure depends on what the investor wants. Fargo, ND has a 56.31% renter share and 6.01% vacancy, compared with 51.31% and 6.23% in Columbia, MO. Columbia’s 50.96% rent-burden share, versus Fargo’s 40.52%, is a material caution rather than straightforward pricing power: financially stretched tenants can limit collections and rent-growth capacity. Check delinquency, concessions, turnover, applicant income and achievable rent by unit type.

04
Housing stockFargo

Fargo, ND better fits housing_stock for an investor seeking multifamily acquisition depth: large multifamily represents 37.04% of its stock versus 10.75% in Columbia, MO. Columbia is more single-family-oriented at 59.27%, compared with Fargo’s 43.53%. That distinction can affect deal availability and comparable-property quality, but not asset condition. The next check is the target building’s age, systems, unit mix, code history and nearby competing pipeline.

05
Local demand riskFargo

Fargo, ND better fits local_demand on the published city evidence. Population change was 7.99% versus 6.04% in Columbia, MO; unemployment was 3.79% versus 4.02%; and poverty was 12.87% versus 19.25%. Fargo’s median household income was also $66,998 compared with $66,498. Verify employer concentration, neighborhood absorption and tenant-income distribution before relying on these citywide signals. The population changes compare overlapping ACS vintages and are not annualized.

Household pressure

Acquisition and renter affordability

FargoColumbiaPrice to incomeZillow value ÷ ACS household income4.8x5.0xRent to incomeAnnual Zillow rent ÷ ACS household income19.5%25.7%Rent-burdened householdsACS renters paying 30% or more40.5%51.0%
Zillow city indexes divided by direct ACS city household measures.
Housing system

Tenure, vacancy and structure

FargoColumbiaRenter shareACS occupied housing56.3%51.3%Vacancy rateACS all housing units6.0%6.2%Single-family stockACS one-unit structures43.5%59.3%Large multifamily stockACS structures with 20+ units37.0%10.7%
ACS citywide housing characteristics; not rentable inventory or lease-up speed.
Underwriting boundary

What this city comparison cannot decide

City evidence narrows a search; it does not appraise, inspect or finance a property.

  1. 01

    Zillow’s 2026-06 rent and value indexes describe city market movement, while ACS surveyed median gross rent and owner value answer different housing questions. They should not be averaged, and ACS medians should not be treated as competing property appraisals.

  2. 02

    Columbia’s 50.96% rent-burden share may reflect renter pressure, but it also signals affordability and collection risk. Property underwriting should test delinquency, bad debt, concessions, applicant income, turnover and realistic renewal increases rather than assuming recent rent growth can continue.

  3. 03

    Gross yield excludes vacancy, management, repairs, taxes, insurance, utilities, financing and capital work. Fargo’s and Columbia’s citywide figures also conceal neighborhood, building-condition and unit-mix differences, so neither yield should advance without matched property operating statements and physical due diligence.