City limitsPlace boundary
Curated city comparison

HattiesburgCharleston

Smaller Southern regional centers with similar population scale and material differences across all six direct-city investment screens.

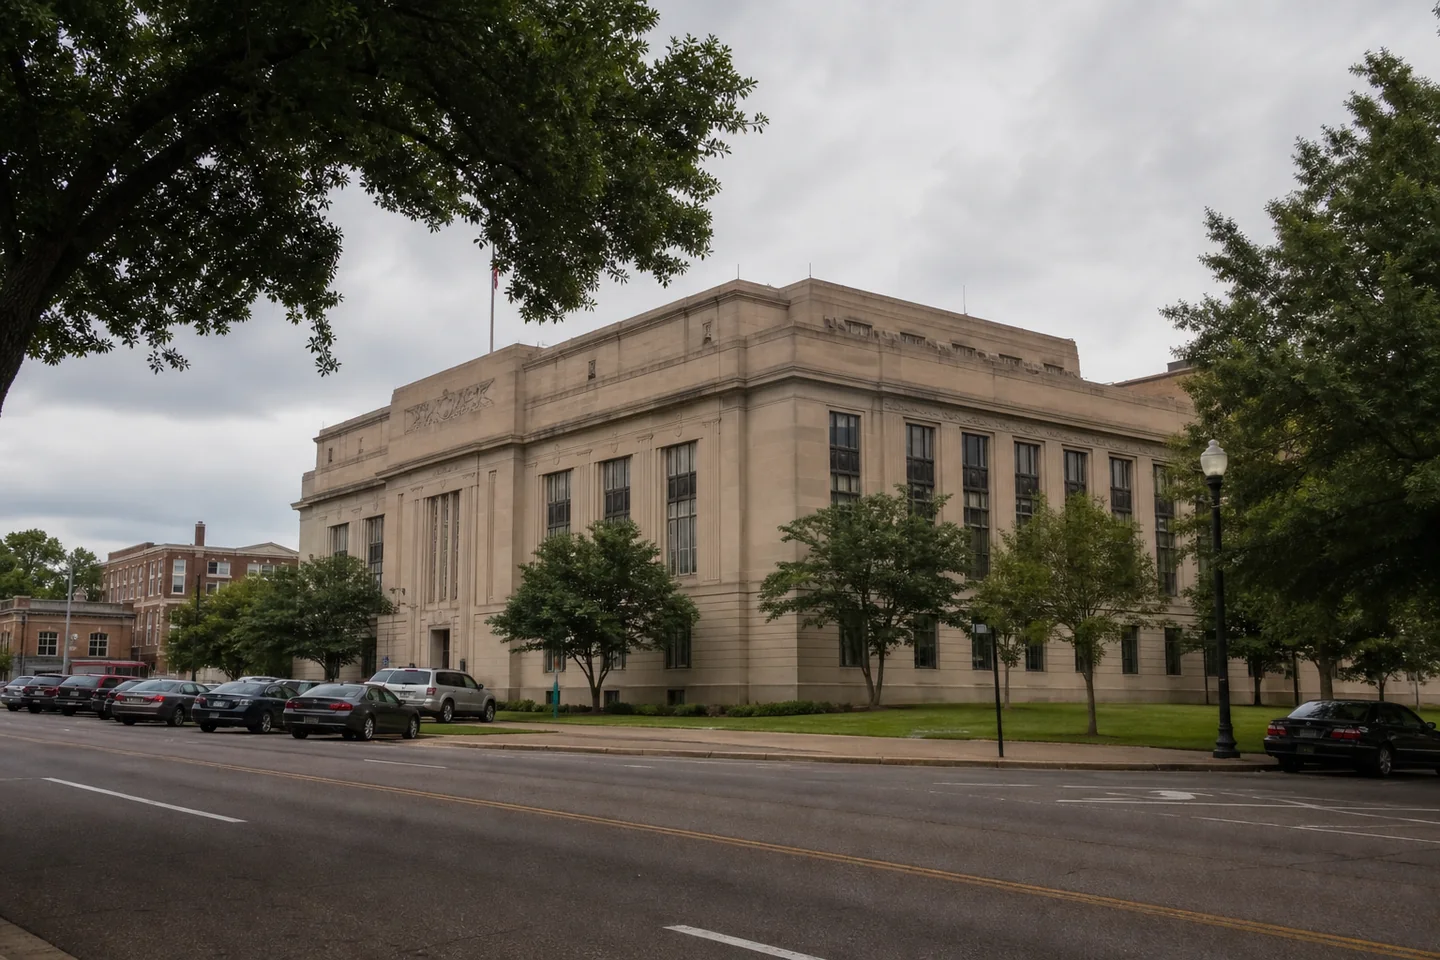
Hattiesburg, MS cityscape
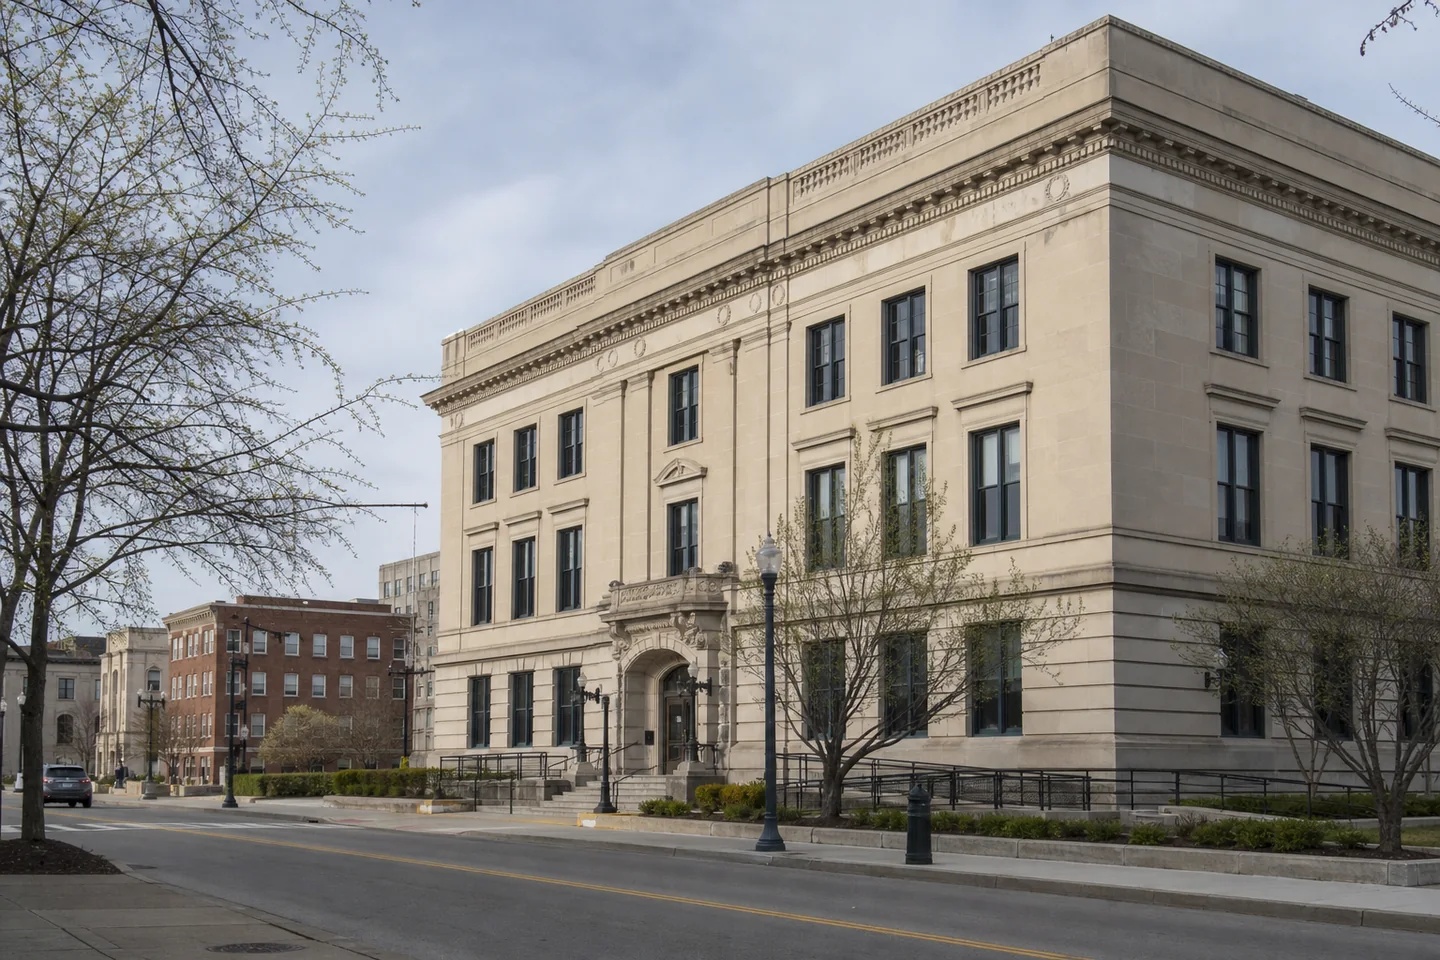
Charleston, WV cityscape
Decision memo

The trade-off before property underwriting

The interpretation uses direct city records only. County and metro averages are not substituted into this comparison.

For cash flow and entry affordability, Charleston, WV deserves the first property-level screen. Its Zillow city indexes show a 9.54% gross yield and a $172,277.67 home-value index, versus 7.57% and $224,680.24 in Hattiesburg, MS. Charleston also has a 2.62 price-to-income measure, compared with 4.85 for Hattiesburg. The yield is only a gross screening metric, so the next step is verifying achievable unit rent, occupancy, taxes, insurance, repairs and capital needs.

For renter pressure, Hattiesburg has the stronger demand-side profile but also greater tenant affordability risk. Renters represent 62.79% of households there versus 36.74% in Charleston, while the ACS rent-burden measure is 51.55% versus 46.78%. Hattiesburg also has the lower city vacancy rate, 11.33% against 17.33%. Underwriting should test whether those signals persist around the specific property and whether household incomes support the asking rent without elevated delinquency or turnover.

Housing-stock preference determines the better fit. Charleston offers more single-family exposure, while Hattiesburg has more large multifamily stock; Charleston’s median year built is 1957, compared with 1981 in Hattiesburg, making inspection scope especially important there. For local demand, Hattiesburg has the more favorable population direction: its ACS population change was 5.47%, while Charleston’s was -1.22%. However, Hattiesburg’s 28.29% poverty rate and 8.66% unemployment rate weaken that signal. Prioritize Charleston for yield-led or lower-entry acquisitions, and Hattiesburg for renter-depth or growth-led searches, subject to address-level validation.

Direct city matrix

The same definition on both sides

“n/a” remains missing. Zillow indexes and ACS survey measures stay visibly separate.

Decision evidenceHattiesburg, MSCharleston, WV
Typical home valueZillow ZHVI · city$224,680$172,278
Observed market rentZillow ZORI · city$1,417$1,370
Gross yieldZORI × 12 ÷ ZHVI · before costs7.6%9.5%
Price to household incomeZillow value ÷ ACS income4.85x2.62x
Annual rent to incomeZillow rent × 12 ÷ ACS income36.7%25.0%
Rent burdenACS renter households paying 30%+51.5%46.8%
Renter shareACS occupied housing62.8%36.7%
Vacancy rateACS all housing units11.3%17.3%
Population changebetween ACS vintages · not annualized▲ 5.5%▼ 1.2%
UnemploymentACS civilian labor force8.7%6.5%
Entry and income screen

Price, rent and yield do not tell the same story

Bars begin at zero within each measure. Gross yield remains a before-cost screen.

HattiesburgCharlestonTypical home valueZillow ZHVI · city$225k$172kObserved market rentZillow ZORI · monthly city index$1k$1kGross yieldZORI × 12 ÷ ZHVI · before costs7.6%9.5%
Zillow city ZHVI and ZORI · 2026-06 / 2026-06
Price and rent history

Two city paths, each rebased to 100

Each panel keeps price and rent in its own city; no level is borrowed across geographies.

Five-year path

Price and rent, rebased to 100

ZHVI +21.0%ZORI +17.6%
12110895202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Five-year path

Price and rent, rebased to 100

ZHVI +26.8%ZORI +24.5%
12711195202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Fit by objective

There is no universal city winner

Five city questions remain separate so a yield lead cannot erase affordability or demand risk.

01
Cash-flow screenCharleston

Charleston, WV better fits a cash-flow-first screen: its Zillow-based gross yield is 9.54%, versus 7.57% for Hattiesburg, MS. That advantage warrants testing Charleston properties first, but it is not a net return forecast. Verify achievable rent, physical vacancy, management, repairs, taxes, insurance, utilities, financing and deferred capital work for each address before treating the city-level spread as investable.

02
Entry affordabilityCharleston

Charleston, WV better fits entry affordability because its Zillow city home-value index is $172,277.67, compared with $224,680.24 in Hattiesburg, MS. Its price-to-income measure is also 2.62 versus 4.85. The next check is not the ACS median home value, which answers a different survey question; obtain actual asking prices, closing assumptions, property taxes, insurance quotes and renovation bids for comparable target properties.

03
Renter pressureHattiesburg

Hattiesburg, MS shows stronger renter pressure than Charleston, WV: renter share is 62.79% versus 36.74%, and city vacancy is lower at 11.33% versus 17.33%. Yet Hattiesburg’s 51.55% rent-burden measure exceeds Charleston’s 46.78%, indicating less tenant headroom. Hattiesburg therefore fits demand-depth screening better, while Charleston may fit affordability-sensitive leasing; verify submarket occupancy, concessions, collections and turnover at the property level.

04
Housing stockDepends on the property

Housing-stock fit depends on strategy. Charleston, WV has a 69.80% single-family share, compared with 51.97% in Hattiesburg, MS, favoring detached-home sourcing. Hattiesburg has a 15.52% large-multifamily share versus Charleston’s 11.07%. Charleston’s median year built is 1957, while Hattiesburg’s is 1981, so Charleston candidates require especially careful systems, structural, environmental and capital-expenditure diligence rather than assuming the lower entry price means lower total basis.

05
Local demand riskHattiesburg

Hattiesburg, MS better fits a population-momentum objective: population change across overlapping ACS vintages was 5.47%, versus -1.22% for Charleston, WV; this is not annualized. The signal is tempered by Hattiesburg’s 28.29% poverty rate and 8.66% unemployment rate, compared with 15.76% and 6.51% in Charleston. Underwriting should confirm employer stability, neighborhood household formation, leasing velocity and tenant payment performance rather than relying on citywide population direction alone.

Household pressure

Acquisition and renter affordability

HattiesburgCharlestonPrice to incomeZillow value ÷ ACS household income4.8x2.6xRent to incomeAnnual Zillow rent ÷ ACS household income36.7%25.0%Rent-burdened householdsACS renters paying 30% or more51.5%46.8%
Zillow city indexes divided by direct ACS city household measures.
Housing system

Tenure, vacancy and structure

HattiesburgCharlestonRenter shareACS occupied housing62.8%36.7%Vacancy rateACS all housing units11.3%17.3%Single-family stockACS one-unit structures52.0%69.8%Large multifamily stockACS structures with 20+ units15.5%11.1%
ACS citywide housing characteristics; not rentable inventory or lease-up speed.
Underwriting boundary

What this city comparison cannot decide

City evidence narrows a search; it does not appraise, inspect or finance a property.

  1. 01

    Zillow city home-value and rent indexes are market indicators, while ACS median home value and median gross rent are survey measures with different definitions. They should not be averaged, and ACS figures should not be treated as competing property appraisals.

  2. 02

    Gross yield excludes vacancy, management, repairs, taxes, insurance, utilities, financing and capital work. Charleston’s older median housing vintage raises particular inspection risk, while neither city record publishes address-level condition, concessions, collections or achievable unit rents.

  3. 03

    Population change compares overlapping ACS vintages and is not annualized. Citywide vacancy, renter share, poverty and unemployment can conceal large neighborhood differences, so parcel-level underwriting should verify submarket occupancy, tenant quality, employer exposure and recent comparable transactions.