City limitsPlace boundary
Curated city comparison

MarionUrbana

Midwestern cities of nearly equal population scale whose direct evidence separates yield, affordability, renter pressure, housing stock and local-demand risk.

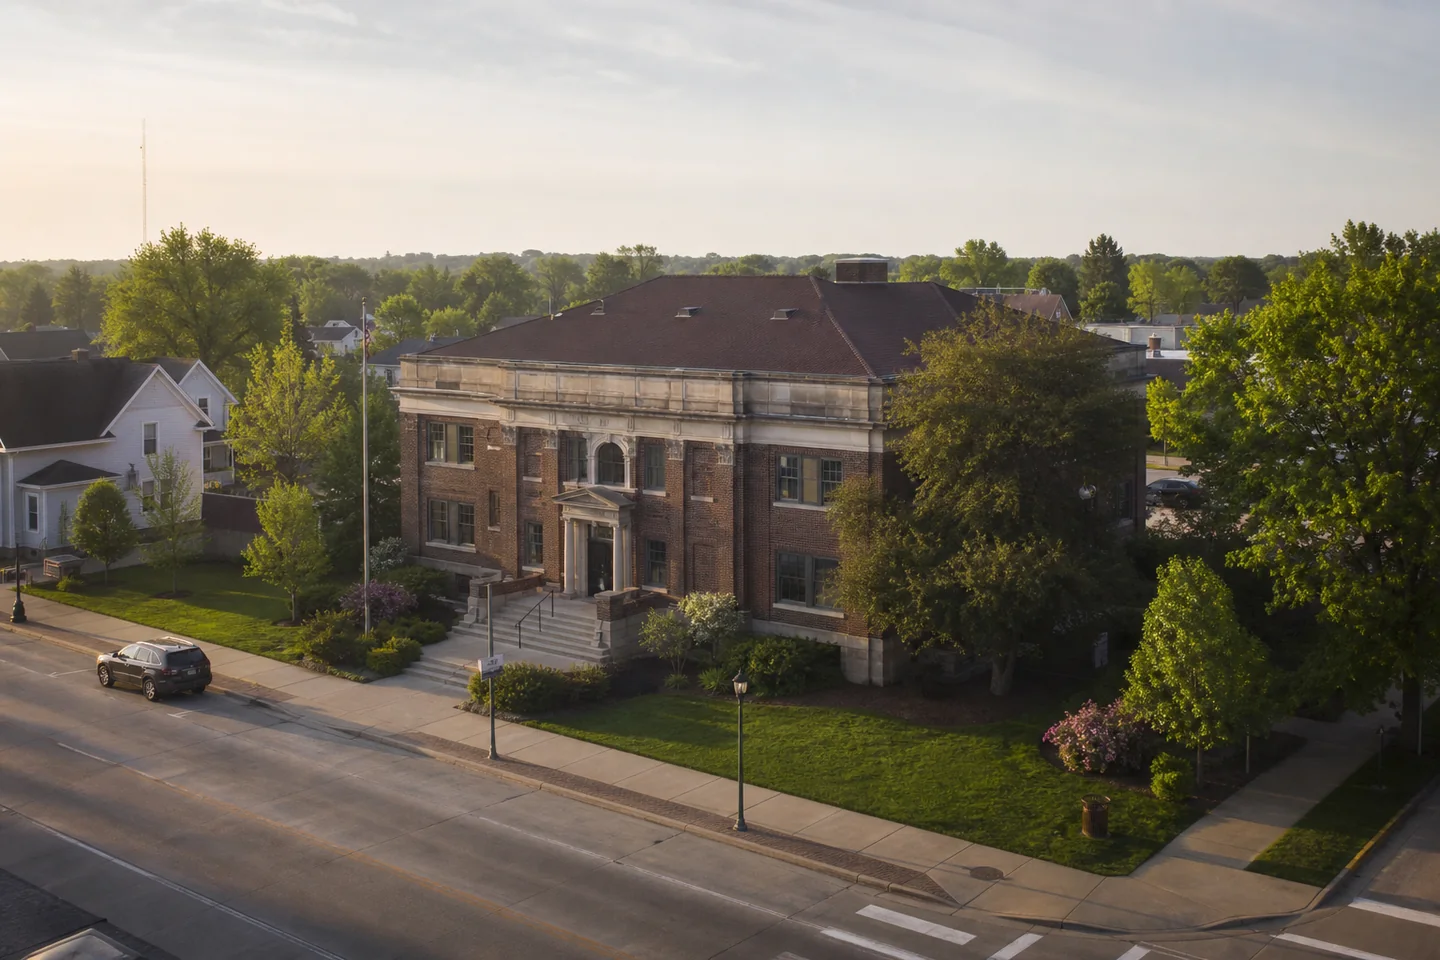
Marion, IA cityscape
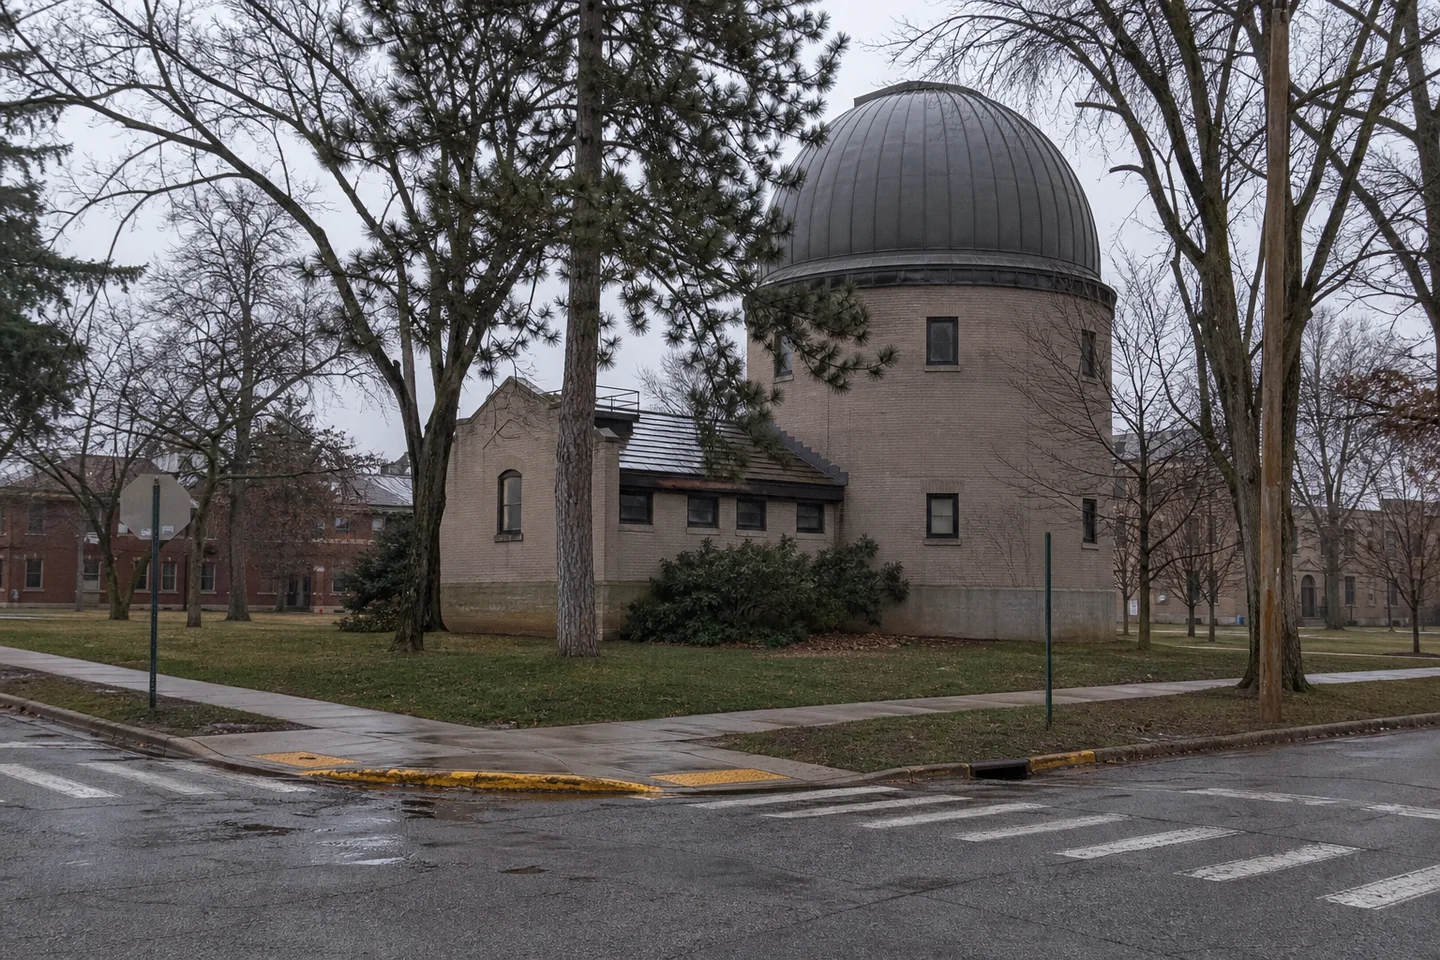
Urbana, IL cityscape
Decision memo

The trade-off before property underwriting

The interpretation uses direct city records only. County and metro averages are not substituted into this comparison.

Marion offers the higher Zillow city rent index, $1,277.6581196581199, but Urbana pairs $1,249.1001443001444 with a lower Zillow city home-value index of $209,776.67993050828 rather than $281,615.99536004785. Urbana’s 7.145313643331154% gross yield exceeds Marion’s 5.4442566077596226%, making Urbana the better cash-flow screen before costs. Gross yield excludes vacancy, management, repairs, taxes, insurance, utilities, financing and capital work; obtain an address-specific operating statement before treating that advantage as investable.

Marion better fits a tightness-and-demand thesis: its vacancy rate is 6.178933939763714% against Urbana’s 12.336176409402955%, and its population change is 6.529698942229456% compared with -7.905332646659491%. The population comparison uses overlapping ACS vintages and is not annualized. Urbana nonetheless has a 62.70170859041291% renter share, versus 22.630801064144251% in Marion, so its leasing universe is more renter-oriented but requires vacancy and concession checks.

For housing type, Marion’s 74.71850906872262% single-family share and 1994 median year built point to a more conventional, newer stock base than Urbana’s 42.635739546494694% and 1980. Urbana’s 22.602454753484502% large-multifamily share, versus Marion’s 5.158355982028953%, may suit an operator pursuing apartment exposure rather than detached homes. Zillow indexes screen current market direction; ACS rent and home-value measures describe surveyed housing and must not be averaged or used as competing appraisals. The next check is property-level condition, layout, lease terms, and block-level supply.

Direct city matrix

The same definition on both sides

“n/a” remains missing. Zillow indexes and ACS survey measures stay visibly separate.

Decision evidenceMarion, IAUrbana, IL
Typical home valueZillow ZHVI · city$281,616$209,777
Observed market rentZillow ZORI · city$1,278$1,249
Gross yieldZORI × 12 ÷ ZHVI · before costs5.4%7.1%
Price to household incomeZillow value ÷ ACS income3.25x4.63x
Annual rent to incomeZillow rent × 12 ÷ ACS income17.7%33.1%
Rent burdenACS renter households paying 30%+54.5%58.3%
Renter shareACS occupied housing22.6%62.7%
Vacancy rateACS all housing units6.2%12.3%
Population changebetween ACS vintages · not annualized▲ 6.5%▼ 7.9%
UnemploymentACS civilian labor force3.6%4.7%
Entry and income screen

Price, rent and yield do not tell the same story

Bars begin at zero within each measure. Gross yield remains a before-cost screen.

MarionUrbanaTypical home valueZillow ZHVI · city$282k$210kObserved market rentZillow ZORI · monthly city index$1k$1kGross yieldZORI × 12 ÷ ZHVI · before costs5.4%7.1%
Zillow city ZHVI and ZORI · 2026-06 / 2026-06
Price and rent history

Two city paths, each rebased to 100

Each panel keeps price and rent in its own city; no level is borrowed across geographies.

Five-year path

Price and rent, rebased to 100

ZHVI +24.4%ZORI +35.6%
13611595202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Five-year path

Price and rent, rebased to 100

ZHVI +35.2%ZORI +39.5%
14011795202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Fit by objective

There is no universal city winner

Five city questions remain separate so a yield lead cannot erase affordability or demand risk.

01
Cash-flow screenUrbana

Urbana fits cash_flow because its Zillow-derived gross yield is 7.145313643331154%, versus 5.4442566077596226% in Marion, a direct comparative advantage before expenses. Marion’s Zillow rent index is $1,277.6581196581199, above Urbana’s $1,249.1001443001444, but its value index is also $281,615.99536004785 rather than $209,776.67993050828. Validate property rent, vacancy, taxes, insurance, repairs and management in both cities; yield is not net cash flow.

02
Entry affordabilityDepends on the property

Entry affordability depends on whether the constraint is acquisition dollars or local purchasing capacity. Urbana’s Zillow city home-value index is $209,776.67993050828 compared with $281,615.99536004785 in Marion, favoring Urbana for nominal entry. Yet Marion’s price-to-income measure is 3.246555864565992 versus 4.626134166861648 in Urbana, favoring Marion on buyer affordability. Check the target property’s price, financing terms and resale buyer pool rather than treating ACS household measures as an appraisal.

03
Renter pressureMarion

Marion fits renter_pressure if the aim is near-term occupancy tightness: Marion’s vacancy rate is 6.178933939763714%, below Urbana’s 12.336176409402955%, and Marion’s Zillow rent growth is 8.967840102176128% against 6.290351719078568%. Urbana has a much larger renter share, 62.70170859041291% versus 22.630801064144251% in Marion, so it may provide a more renter-centric customer base. Inspect submarket vacancies, concessions, lease-up competition and unit type before deciding.

04
Housing stockMarion

Marion fits housing_stock for a detached-home strategy. Its single-family share is 74.71850906872262%, versus 42.635739546494694% in Urbana, and its median year built is 1994 rather than 1980. Urbana’s large-multifamily share is 22.602454753484502%, compared with Marion’s 5.158355982028953%, which is a reason to select Urbana only when apartment exposure is the intended operating model. Verify construction condition, systems, layout and maintenance history at the address.

05
Local demand riskMarion

Marion fits local_demand. Its ACS population change is 6.529698942229456% while Urbana’s is -7.905332646659491%, and Marion’s unemployment rate is 3.555009331330511% versus 4.715495176215491%. Marion’s poverty rate is also 8.149324096791263%, compared with 28.022110069694783% in Urbana. These city measures support a stronger screen, not a substitute for checking the property’s employment access, school-area demand, tenant profile and local absorption.

Household pressure

Acquisition and renter affordability

MarionUrbanaPrice to incomeZillow value ÷ ACS household income3.2x4.6xRent to incomeAnnual Zillow rent ÷ ACS household income17.7%33.1%Rent-burdened householdsACS renters paying 30% or more54.5%58.3%
Zillow city indexes divided by direct ACS city household measures.
Housing system

Tenure, vacancy and structure

MarionUrbanaRenter shareACS occupied housing22.6%62.7%Vacancy rateACS all housing units6.2%12.3%Single-family stockACS one-unit structures74.7%42.6%Large multifamily stockACS structures with 20+ units5.2%22.6%
ACS citywide housing characteristics; not rentable inventory or lease-up speed.
Underwriting boundary

What this city comparison cannot decide

City evidence narrows a search; it does not appraise, inspect or finance a property.

  1. 01

    Gross yield is a pre-cost screen: it excludes vacancy, management, repairs, taxes, insurance, utilities, financing and capital work. Underwrite each candidate in Marion and Urbana with property-specific recurring and capital expenses before relying on the comparative yield.

  2. 02

    Zillow city home-value and rent indexes are market indicators, while ACS median rent and home value are survey measures for different housing populations. They should not be averaged or treated as competing property appraisals for either Marion or Urbana.

  3. 03

    Population change uses overlapping ACS vintages and is not annualized, so it cannot establish current absorption. For Marion and Urbana, verify listing-level availability, concessions, condition, tenant mix, and block-level rent evidence before an offer.