States / Rhode Island
State rental intelligence

Rhode Island rental market data

A source-traced view across 1 metro markets and 5 counties. State figures below are labelled medians and totals—not a made-up statewide investment score.

1/1 metros scored5/5 counties with FEMA risk14 sources used in this analysis
Median scored metro52.0out of 100 · 1 measured metros
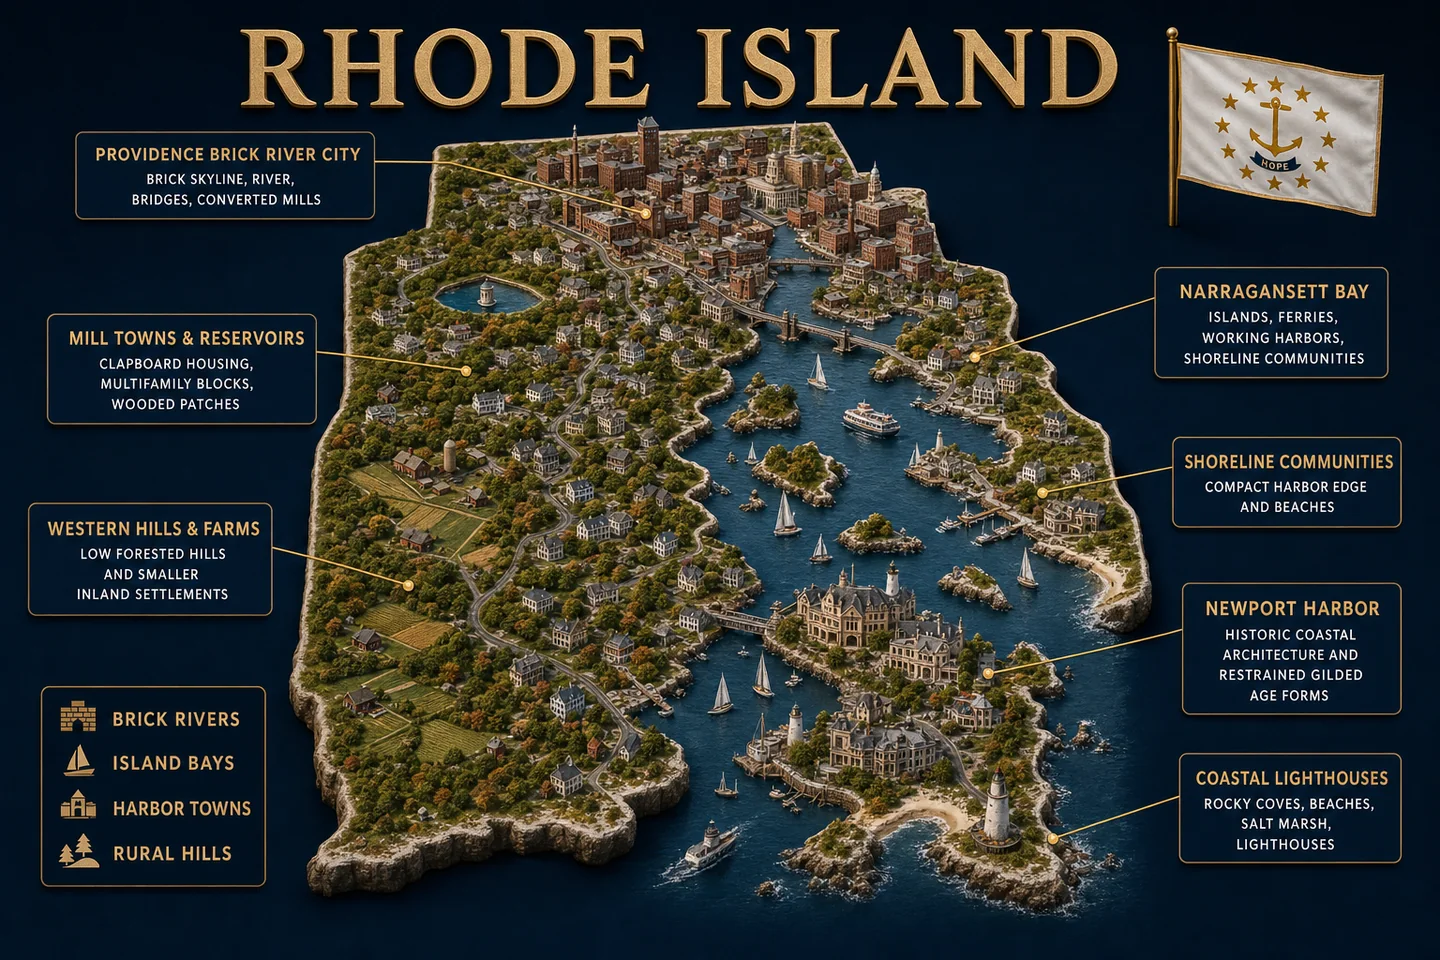
Rhode Island identity diorama showing regional landscape, cities, housing, and infrastructure
Median metro home value$532kmedian across published metro values
Median metro rent$2,172monthly · published metro values
Median gross yield4.9%annual rent ÷ price · before costs
Median job trend▼ 0.3%trailing 12-month metro employment
Direct monthly rental evidence

Rhode Island rent market dynamics

Apartment List measures recent leases, rental vacancy and listing time separately. These figures do not replace Zillow, Census or Realtor measures elsewhere on this page.

Recent-lease rent$1,5372026-07 · ▲ 1.7% year over year
Rental Vacancy Index5.8%2026-07 · +0.8 pp in 12 months
Time on marketn/anot published for this state
US recent-lease rent$1,3882026-07 · ▼ 1.1% year over year
Rent and rental vacancy through timesolid state series · dashed national series · no interpolation across missing observations
Recent-lease rent$1,611$1,231$850Rental Vacancy Index10.4%5.9%1.4%2017-012021-102026-07Rhode IslandUnited States
State research brief

Recent-lease rents rose 1.7% even as rental vacancy climbed 0.8 percentage point, making locality-level demand and affordability checks more important than the still-below-national 5.8% vacancy rate.

Updated 2026-08-08 · evidence current to the releases listed below.

The clearest tension is between positive recent-lease rent growth and loosening rental vacancy. Apartment List shows rent up 1.7% while its separate Vacancy Index rose from 5.0% to 5.8%. Vacancy remained 1.4 percentage points below the national rate, but the increase weakens the case that rent growth reflects an unambiguously tightening market.

Screening should move quickly from the state signal to county and property economics. Across five measured counties, 10th-to-90th percentile gross yields ran from 4.2% to 5.9%, ACS vacancy from 5.6% to 18.7%, and renter cost burden from 46.4% to 50.7%. The packet covers one metro and five counties; it cannot establish neighborhood demand, achievable property rent, operating costs, state rental listing time or parcel-level hazard exposure.

01

Separate Apartment List measures show recent-lease rent up 1.7% while vacancy rose 0.8 percentage point to 5.8% → stress-test rent growth against looser occupancy.

02

County gross yields span 4.2% to 5.9% from the 10th to 90th percentile → avoid using one statewide acquisition yield.

03

Median county renter cost burden is 49.5% → test tenant affordability before assuming aggressive rent increases.

04

Net migration is negative 129 and measured metro jobs are down 0.3% → verify employer and renter demand at the submarket level.

05

All five counties have inland flood as the leading hazard label, while tax rates span 0.93% to 1.33% from the 10th to 90th percentile → obtain parcel insurance and tax inputs before comparing net returns.

01
Direct state rental dynamics

Rent gains persisted while rental vacancy loosened

Apartment List's recent-lease rent measure reached $1,537, up from $1,511 a year earlier, for 1.7% growth. The national comparator fell 1.1%, leaving Rhode Island's growth rate 2.8 percentage points stronger. That supports continued testing of rent resilience, but not automatic application of the state gain to every unit.

The separate Vacancy Index moved in the opposite direction, rising from 5.0% to 5.8%, an increase of 0.8 percentage point. Current vacancy was still 1.4 percentage points below the national 7.2%, but the increase is a genuine counter-signal. No state time-on-market figure is supplied; the national move from 28 to 30 days cannot serve as a Rhode Island lease-up estimate.

Evidence: Apartment List Rent Estimates — recent-lease rent index · Apartment List Time on Market — listing liquidity · Apartment List Vacancy Index — rental vacancy

02
Housing stock and tenant conditions

County vacancy varies sharply beneath a common affordability strain

Across five counties, the 10th-to-90th percentile range for ACS housing vacancy was 5.6% to 18.7%, while renter shares ranged from 24.3% to 38.7%. Washington County stood above that vacancy band at 20.8%. These are broad ACS housing-stock vacancy measures, not the Apartment List Vacancy Index or a count of apartments currently available to rent.

Affordability pressure is more consistent: the median county share of renters spending at least 30% of income on rent was 49.5%, with a 46.4% to 50.7% 10th-to-90th percentile range. Washington County measured 51.3%. The median county single-family share was 70.5%, and the median across county median-year-built figures was 1963. Screening therefore needs unit-type, condition and rehabilitation checks alongside rent assumptions; these aggregates do not reveal a particular property's tenant base or physical condition.

Evidence: Census ACS 5-year — county housing value, tenure and stock

03
County market dispersion

Kent leads the highlighted county yield set while resale signals split

Across five counties, the 10th-to-90th percentile range for headline gross yield was 4.2% to 5.9%. Among the three highlighted county profiles, Kent County measured a 6.1% gross yield on a $449,155 value and $2,289 monthly rent. Newport County measured 4.7% on $800,321 and $3,135, while Bristol County measured 4.1% on $661,879 and $2,271. The spread makes county selection consequential, but these are gross figures before vacancy, maintenance, taxes, insurance and financing.

For-sale listing conditions are not uniform either. Washington County had a 32-day median listing time and a 0.75 pending ratio, compared with 31 days and 1.23 in Kent County. Providence County had a 29-day median and a 9.1% price-reduced share. These are resale indicators, not rental listing time, and county listing coverage is incomplete, so they should inform exit-liquidity screening rather than lease-up assumptions.

Evidence: FHFA House Price Index — annual county appreciation · Realtor.com Economic Research — county listing inventory · Zillow ZHVI and ZORI — county values and rents

04
Employment and household movement

Nearly flat migration and softer jobs temper the rent signal

Providence, RI, the sole measured metro, recorded a 0.3% year-over-year job decline. Across five counties, 26,761 movers came in and 26,890 moved out, producing net migration of negative 129, or negative 0.12 per 1,000 residents. Those measures do not supply a broad demand tailwind for the positive rent signal.

The income flow is a counter-signal within the migration data: aggregate incoming mover AGI was $480,850 versus $425,125 outgoing, a positive gap of $55,725. The combination points to nearly balanced headcount with a positive measured income gap, not a simple expansion or contraction story. Because the job and migration series have different coverage, they cannot establish current renter-household formation in a specific submarket.

Evidence: Census ACS 5-year — population · BLS CES — payroll employment · BLS LAUS — resident employment · IRS SOI — county migration and mover income

05
Investor participation

Newport has the highest highlighted investor share

The HMDA measure records 866 investor purchases among 10,214 purchases across five counties. County investor shares had a 9.2% median and a 6.9% to 12.1% 10th-to-90th percentile range, showing that non-occupant participation is not evenly distributed.

Among the highlighted counties, Newport County had a 13.7% investor share, with 102 investor purchases out of 746, and a 4.7% gross yield. Washington County measured 9.7% and 4.3%, while Bristol County measured 9.2% and 4.1%. These figures can flag where investor-coded financing is more visible, but HMDA purchase originations do not capture all-cash activity or prove that a non-occupant purchase became a long-term rental.

Evidence: HMDA / CFPB — purchases by occupancy type

06
Physical risk and property tax

Inland flood leads every county hazard profile while tax burdens vary

Inland flood is the mutually exclusive leading-hazard label in all five counties. County climate-loss ratios had a 0.095% median and a 0.071% to 0.105% 10th-to-90th percentile range. That establishes a county-level screening theme, not flood exposure for every parcel or building.

Effective property-tax rates had a 1.25% county median and a 0.93% to 1.33% 10th-to-90th percentile range. The median tax measured $5,102 across counties; Bristol County was $6,648, compared with $4,683 in Providence County. Property underwriting needs the actual assessment, insurance terms and parcel hazard information because county distributions cannot determine a building's operating burden.

Evidence: FEMA National Risk Index — hazard loss ratios · Census ACS 5-year — effective property tax

Evidence selected for Rhode Island

The ranges behind the analysis

Each row keeps its own unit and shows the measured 10th percentile, median and 90th percentile. A single-value row is labelled directly.

Housing stock and tenant conditionsWhat kind of housing exists, how much is vacant and how burdened are renters?
10th pct.median90th pct.Vacancy rate5.6%7.0%18.7%Renter share24.3%28.2%38.7%Rent burden 30%+46.4%49.5%50.7%Single-family share57.1%70.5%76.7%
County market dispersionWhere do county appreciation, listing conditions and measured rents diverge?
10th pct.median90th pct.Five-year HPI change65.2%65.8%66.8%Listing days28 days30 days32 daysGross yield4.2%4.7%5.9%Reduced-price share6.2%6.7%8.5%
Employment and household movementDo jobs, household movement and mover income point in the same direction?
10th pct.median90th pct.Job change-0.3%-0.3%-0.3%Net migration / 1k-0.1Net household movement-129
Shape of the state

Distribution before conclusion

A statewide median can hide a wide spread. These SVG charts render at build time and carry no chart library or browser-side data request.

Metro score distribution1 scored metros · median 52.0
00–19020–39140–59060–79080–100
County evidence coverageEvery gap stays visible as missing—not estimated
100%5/5Rent100%5/5Climate100%5/5Migration
Highest measured metro gross yieldsscreening metric only · before expenses and financing
Providence4.9%
Metro leaderboard

Markets touching Rhode Island

Multi-state CBSAs appear in every member state. Score is still a metro score; no value is reweighted into a statewide ranking.

#MetroScorePriceRentYieldJobs
1Providence, RI52$532k$2,1724.9%▼ 0.3%
Below the metro line

Largest counties in Rhode Island

County figures join on the five-digit FIPS code. The table uses measured local values and prints “n/a” wherever a publisher has no record.

CountyPopulationPriceRentYieldHazard
Providence County, RI664,854$460k$2,1105.5%inland flooding
Kent County, RI171,456$449k$2,2896.1%inland flooding
Washington County, RI130,344$695k$2,5164.3%inland flooding
Newport County, RI84,657$800k$3,1354.7%inland flooding
Bristol County, RI50,490$662k$2,2714.1%inland flooding
County yield sample5/5counties have the rent needed to compute yield
Statewide net migration−129IRS tax-return households summed across counties
Median investor share9.2%among counties with HMDA purchase records
Bear case

What can break the thesis

  1. Coverage is limited to one measured metro and five county aggregates, so neighborhood and property-type differences can overturn the state-level reading.
  2. Rhode Island rental time on market is missing; national rental time and county for-sale listing days are not substitutes.
  3. ACS housing vacancy is broader than available rental inventory and cannot validate the Apartment List Vacancy Index.
  4. Gross yields use measured rents and values before operating expenses, financing and capital work; the older housing-stock profile may make net results materially different.
  5. FEMA leading-hazard labels and county loss ratios do not establish parcel exposure, building vulnerability or an obtainable insurance premium.
Investor questions

Before underwriting a property

Did rent growth coincide with tighter rental vacancy?

No. In separate Apartment List series, recent-lease rent rose 1.7%, but the Vacancy Index increased from 5.0% to 5.8%. Vacancy remained below the 7.2% national rate, yet its direction was looser.

Which highlighted county has the strongest headline gross yield?

Kent County measured 6.1% on a $449,155 value and $2,289 monthly rent, versus 4.7% in Newport County and 4.1% in Bristol County. This is a gross comparison, not a net-return ranking.

Do employment and migration confirm expanding rental demand?

Not clearly. The sole measured metro had a 0.3% job decline, and five-county net migration was negative 129. Incoming mover AGI exceeded outgoing AGI by $55,725, so the evidence is mixed rather than uniformly weak.

Where is measured investor participation highest among the highlighted counties?

Newport County had a 13.7% investor share, above Washington County at 9.7% and Bristol County at 9.2%. The HMDA measure covers purchase originations and does not establish all-cash activity or subsequent rental use.

Does the inland-flood label establish that a property is exposed?

No. It is the mutually exclusive leading county hazard in all five counties, but it is not parcel-level exposure evidence. A property decision still requires parcel, building and insurance review.