Cities / Minnesota / Hennepin County / Minneapolis
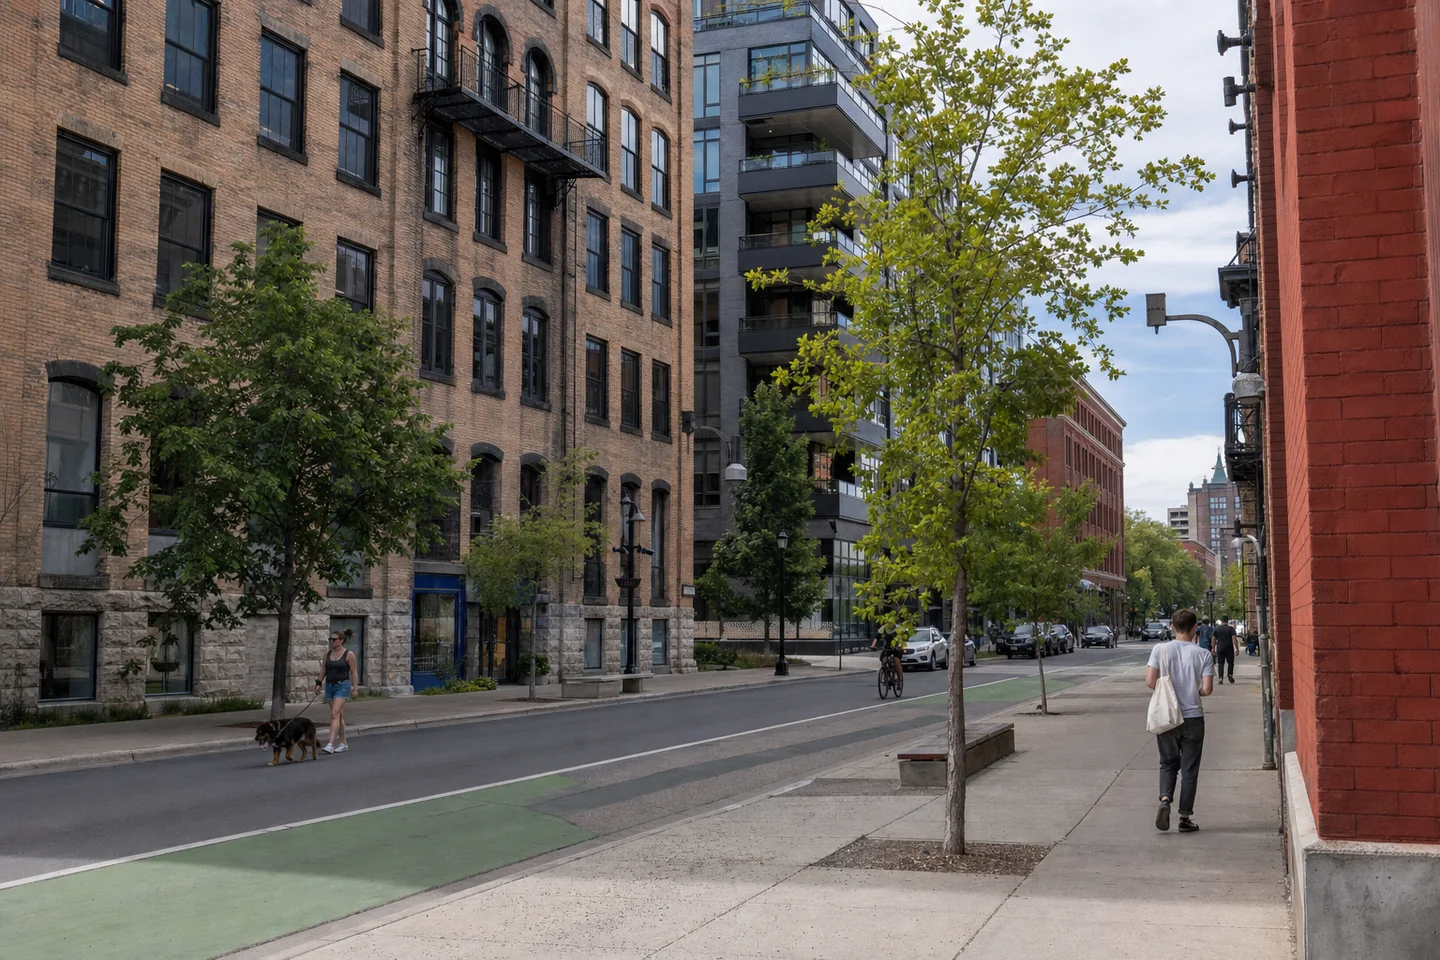
Minneapolis cityscape
City housing brief · Incorporated place

Minneapolis, MN

City evidence stays city-level. County, metro and national records appear separately to explain the wider market without changing the city figures.

City gross yield6.0%ZORI × 12 ÷ ZHVI · before costs
Direct city rent answer

What does rent cost in Minneapolis, MN?

The latest city-level Zillow ZORI for Minneapolis is $1,686 per month in 2026-06. It measures a typical asking-rent market across rental types—not an arithmetic average or an address-level rent estimate.

City Zillow ZORI$1,6862026-06 · up 3.6% year over year
City ACS gross rent$1,371ACS 2024 5-year occupied-renter survey
HUD two-bedroom context$1,709Hennepin County administrative standard
How to read the rent answer for Minneapolis
MeasureCurrent valueGeographyMeasurement boundary
Zillow ZORI$1,686Minneapolis cityTypical observed asking-rent index; not a unit quote.
Census ACS gross rent$1,371Minneapolis citySurvey estimate for occupied renter homes, including specified utilities.
HUD 2BR FMR$1,709Hennepin CountyAdministrative bedroom standard; wider context, never substituted as city rent.

For a property decision, match bedroom count, condition, utilities, concessions, lease timing and nearby comparable listings. Wider county and metro evidence below stays explicitly labelled.Zillow pulled 2026-07-29

For within-city variation, inspect the published ZIP rental landscape rather than treating one citywide value as uniform.

City market snapshot

Four figures that frame the city

Typical home value
$337k
▲ 0.9% year over year
Zillow ZHVI · 2026-06
Observed market rent
$1,686
▲ 3.6% year over year
Zillow ZORI · 2026-06
Entry affordability
4.2x
home value ÷ household income
Zillow + Census ACS
Population
427,246
▲ 1.6% between ACS vintages
ACS 2024 5-year
Decision brief

What the city-level evidence says

01Decision frame

Minneapolis’s current Zillow ZHVI typical home value is $336,624, while ZORI typical observed market rent is $1,686 a month; the implied gross yield is 6.0% before every operating cost, financing and vacancy. ZHVI is 4.16x ACS median household income, and annualized ZORI equals 25.0% of that income, giving a citywide affordability screen rather than a household budget. ZHVI rose 0.9% year over year while ZORI rose 3.6%; neither change establishes a property’s future performance.

02Housing stock

City housing is majority renter-occupied, with renters in 52.3% of occupied units, while 7.8% of all housing units are vacant. These citywide stock measures do not show whether a particular rental will lease quickly. The ACS median owner-reported home value is $362,200 and median gross rent is $1,371, including selected utilities. Those surveyed occupied-housing measures differ in concept and period from Zillow’s typical value and observed market rent and must not be combined.

03City depth

Direct city evidence shows a mixed structure profile: single-family homes are 43.8% of units and large multifamily buildings 33.6%. Among applicable renter households, 48.1% meet the ACS rent-burden threshold, while 45.1% of vacant units are classified as for rent. These survey shares do not establish lease-up speed or available investment inventory. The population is 427,246, up 1.6% between overlapping ACS vintages; the change is not annualized, and boundary changes may affect comparability. Median household income is $80,846, the poverty rate is 16.0%, and unemployment is 5.9%. These citywide facts describe demand constraints and labor conditions, not tenant quality, rent collection or causation at an address.

04Wider context

In Hennepin County, the property-tax rate is 1.14%, and Realtor listings had 37 median days on market; both are county context, not Minneapolis or property-level results. In the broader Minneapolis metro, payroll jobs increased 0.22% year over year and months of supply was 2, providing labor and sale-inventory context, neither specific to the city. Nationally, Freddie Mac’s 30-year mortgage rate was 6.58%, a financing benchmark rather than a local borrowing quote or an investor’s actual cost.

05Limits & next checks

The main underwriting gap is the distance between citywide typicals and a specific asset’s achievable rent, condition and expenses. Verify unit-level leases and concessions; inspect structure, systems and deferred maintenance; obtain insurance and hazard terms; confirm assessed value, taxes and special assessments; and price management, utilities, repairs, turnover and vacancy. Test debt service with an actual lender quote and compare the resulting net cash flow—not gross yield—with realistic capital reserves and exit costs.

Local rent intelligence

Minneapolis Rent Intelligence: Market Pricing, Supply Pipeline, and Tenant Absorption

Budget context

What the rent asks of an annual income

Median household income$80,846
Income at the rent budget$67,447
$1,686 monthly rent × 12 ÷ 30% = $67,447 annual income. A gross-income budgeting screen, not a lender or landlord qualification rule. Zillow ZORI: 2026-06; Census: ACS 2024 5-year.
Chart data and calculation
Annual income references, not equivalent household samples
MeasureAnnual amountBasis
Median household income$80,846ACS 2024 5-year
Income at the rent budget$67,447City ZORI × 12 ÷ 0.30

Put the benchmark to work

Match the rent period and housing type to your actual options. Check utilities, recurring fees and lease terms before treating the difference as savings.

Explore the metro rent budget tool →See the salary-to-rent research →Compare published city alternatives ↓

Market Rent Trajectory and Divergent Rent Benchmarks

Minneapolis asking rents registered upward movement over the five-year stretch ending in June 2026. According to the Zillow Observed Rent Index (ZORI), the typical market asking rent in Minneapolis reached $1,686.18 per month in June 2026, representing a 3.60% increase over the June 2025 level of $1,627.65. The annual June snapshots track the index at $1,457.20 in June 2021, $1,519.52 in June 2022, $1,537.43 in June 2023, and $1,576.68 in June 2024. Because these data points reflect annual June snapshots, they illustrate medium-term pricing momentum across consecutive summer cycles but cannot establish within-year monthly seasonality or the best calendar month to execute a lease.

Market participants must evaluate asking rents alongside alternative rental metrics that reflect distinct measurement universes and methodologies. The Apartment List rent estimate for Minneapolis stood at $1,462.00 per month as of July 1, 2026, paired with an Apartment List rental vacancy rate of 9.13% and a time-on-market index of 30.7 days. The Apartment List figure reflects a separate recent-lease rent estimate with its own measurement universe, whereas ZORI measures typical market asking rents based on advertised rents. ZORI does not represent an arithmetic mean or an executed transaction benchmark, and the numerical difference between the indices illustrates variance in measurement universes and methodology rather than a measurement error.

A wider divergence appears when comparing open-market listings to survey estimates. According to the Census Bureau's ACS 2024 5-year estimates, the median gross rent across renter-occupied housing units in Minneapolis was $1,371.00 per month. This produces an asking-versus-survey rent gap of $315.18, or a 22.99% difference between current advertised market rents ($1,686.18) and the survey median gross rent ($1,371.00). The ACS gross rent figure reflects monthly contract rent plus selected tenant-paid utilities estimated over the five-year survey window. The underlying survey data does not observe tenure duration, subsidy mix, or the specific causes of the gap from ZORI asking rents.

Regarding close geographical substitutes, this data packet cannot support a measured local substitute within the metropolitan footprint because no alternative city profiles were captured in the same-metro screening dataset. Tenants evaluating locations must therefore assess the Minneapolis market on its own structural fundamentals and countywide relationships.

Income Screens, In-Place Rent Burden, and Household Capacity

Underwriting rent affordability requires distinguishing between hypothetical tenant income screening scenarios and aggregate community rent burden. Under the 30% gross income scenario assumption, supporting the typical June 2026 asking rent of $1,686.18 corresponds to an annual household income of $67,447.06. When evaluating the broader municipal population, the ACS 2024 5-year median household income for Minneapolis stood at $80,846.00. In a scenario where exactly 30% of that median household income is allocated toward gross rent, monthly rent would equal $2,021.15, yielding an asking-rent-to-income ratio of 25.03%. This screen represents an analytical scenario assumption rather than evidence of adequate take-home income or actual spending.

However, evaluating market asking rents against the entire city median household income does not capture the distribution of rent burden among existing renters. The ACS 2024 5-year data reveals that 48.10% of renter households in Minneapolis are rent burdened, paying 30% or more of their total household income toward gross rent. In total, renter households occupy 100,754 units in the city, representing a 52.28% share of the 192,734 total occupied housing units, alongside 91,980 owner-occupied units.

Socioeconomic baseline indicators from the ACS 2024 5-year release report an individual poverty rate of 15.97% and an unemployment rate of 5.95% against a population of 427,246 residents (reflecting a 1.65% increase over the baseline population of 420,324). Alongside these baseline conditions, 48.10% of renter households pay 30% or more of their household income toward gross rent, while the annual income corresponding to the June 2026 asking rent under a 30% screen stands at $67,447.06.

Housing Inventory Structure, Vacancy Composition, and County Context

The physical profile of Minneapolis housing outlines the composition of the local residential stock. The ACS 2024 5-year survey counted 209,080 total housing units across the city, with a median year built of 1951. Single-family detached and attached residences accounted for 91,551 units, or 43.79% of all housing units. Meanwhile, units in large multifamily buildings containing 20 or more units comprised 70,258 units, or 33.60% of all housing units in the city.

Citywide vacancy indicators must be interpreted with analytical precision to avoid conflating overall housing slack with rental market availability. The ACS 2024 5-year data records 16,346 vacant housing units in Minneapolis, producing an overall gross vacancy rate of 7.82%. Of these vacant properties, 7,374 were classified as vacant for rent, meaning the for-rent vacancy share represents 45.11% of all vacant homes in the city—not a rental vacancy rate. For comparison, 739 vacant units were classified for sale, and 1,502 units were designated for seasonal or recreational use. By contrast, the Apartment List rental vacancy index registered at 9.13% as of July 1, 2026, accompanied by a time-on-market index of 30.7 days.

Broadening the geographical scope to Hennepin County illustrates how Minneapolis compares to the broader county in which it resides. In Hennepin County, typical June 2026 asking rent reached $1,766.00 according to Zillow, which is $79.82 higher per month than the Minneapolis city figure of $1,686.18. Hennepin County home prices were also elevated relative to the city core, with the countywide typical home value registering at $395,883 compared to the Minneapolis citywide typical value of $336,624.39. For voucher administration, HUD established the FY2026 Fair Market Rent (FMR) for a two-bedroom unit in Hennepin County at $1,709.00. This administrative benchmark provides an external reference for public subsidy calculations across the county, sitting slightly below the countywide typical market asking rent of $1,766.00 but above the citywide asking level.

Asset Pricing, Regional Pipeline Pressures, and Underwriting Constraints

Real estate asset valuations in Minneapolis show modest capital appreciation alongside unadjusted rental returns. As of June 2026, typical home values in the city reached $336,624.39, recording a modest 0.94% year-over-year increase. When measured against the typical annual asking rent implied by the June 2026 index ($20,234.12 annualized), the city generated an estimated gross rental yield of 6.01%, accompanied by a price-to-income ratio of 4.16. In Hennepin County as a whole, the gross yield recorded in June 2026 was slightly lower at 5.35%, reflecting the county's higher base purchase prices.

Over a longer horizon, Hennepin County experienced a 3.01% annual home price appreciation in 2025 according to the FHFA House Price Index, building on a cumulative five-year appreciation rate of 29.82%. At the national level, Freddie Mac reported a 30-year fixed mortgage rate of 6.69% for the week of August 6, 2026. According to HMDA purchase origination records for 2024, investors accounted for an 8.07% share of home purchases across Hennepin County.

Operating underwriting must also incorporate broader regional supply and liquidity variables. In the Minneapolis, MN metropolitan area, the Redfin tracker recorded a median days on market of 22 days as of May 1, 2026, with 33.84% of active listings having experienced price drops, an overall sale-to-list ratio of 100.59%, and an inventory level sitting at 2 months of supply. Metropolitan employment growth showed slight expansion, with BLS payroll data showing a 0.22% year-over-year job growth rate for the 12 months ending June 2026. Meanwhile, regional supply additions remain active: the Census Building Permits Survey recorded 13,906 total residential building permits across the Minneapolis metro through June 2026 year-to-date, representing 3.74 permitted units per 1,000 residents.

In Hennepin County, Realtor.com recorded 3,108 active listings in June 2026, with a median days on market of 37.0 days and 15.55% of listings featuring price reductions. County demographic and property fundamentals introduce additional operational risks: IRS migration records from 2022 to 2023 showed a net outflow of -2,068 individuals from Hennepin County, the effective property tax rate was 1.14% based on ACS 2024 5-year data, and the FEMA National Risk Index indicates a countywide annual climate loss ratio of 0.10%. Aggregate market yields of 6.01% do not guarantee single-property profitability, requiring investors and housing providers to independently verify localized property taxes, heating and physical maintenance costs for older inventory built before 1951, and concessions in buildings competing against newly permitted metro supply.

Local rent questions

What annual income is required to comfortably lease a typical market-rate rental in Minneapolis?

Applying the 30% gross income scenario assumption to the June 2026 Zillow Observed Rent Index figure of $1,686.18 per month corresponds to an annual household income of approximately $67,447.06. For comparison, the Minneapolis citywide median household income was $80,846.00 in the ACS 2024 5-year survey, where allocating 30% of monthly earnings toward housing corresponds to $2,021.15 per month. This scenario calculation serves as an analytical screen rather than evidence of actual spending, lease approval, or adequate take-home income. Meanwhile, ACS survey estimates show that 48.10% of Minneapolis renter households pay 30% or more of their household income toward gross rent.

Why do Apartment List and Zillow metrics show different rent figures for Minneapolis?

As of June 2026, Zillow ZORI reported a typical asking rent of $1,686.18, whereas Apartment List recorded an estimate of $1,462.00 as of July 1, 2026. This difference reflects distinct measurement universes and methodologies rather than data errors. Zillow ZORI measures typical market asking rents based on advertised rents. In contrast, Apartment List provides a separate recent-lease rent estimate with its own measurement universe. Additionally, both metrics differ from the ACS 2024 5-year median gross rent of $1,371.00, which estimates monthly contract rent plus selected tenant-paid utilities for renter-occupied units across a five-year survey window without observing tenure duration or the causes of the divergence from asking rents.

How does metropolitan construction activity compare to rental vacancy in Minneapolis?

Metropolitan builders permitted 13,906 residential units across the Minneapolis metro area during the first six months of 2026, translating to a construction intensity of 3.74 permits per 1,000 residents. Locally within Minneapolis, the Apartment List rental vacancy index reached 9.13% with a time-on-market index of 30.7 days as of July 1, 2026. Concurrently, the ACS 2024 5-year estimates revealed that 7,374 housing units were vacant for rent, representing 45.11% of the city's 16,346 total vacant units. In Minneapolis, 33.60% of all housing units are located in large multifamily buildings with 20 or more units, while metro employment expanded at 0.22% over the 12 months ending June 2026.
Sources and release periods for this analysis
Housing system

Market movement and the stock underneath it

Five-year path

Price and rent, rebased to 100

ZHVI +3.5%ZORI +15.7%
11610595202120222023202420252026
Each series starts at 100 so their direction can be compared without pretending that a home value and a monthly rent share the same unit.
Housing stock

Tenure and vacancy

ACS
52.3%RENTER
Owner occupied47.7%
Renter occupied52.3%
Vacant units7.8%

Median structure year 1951

Tenure uses occupied units; vacancy uses all housing units.
Measurement matrix

Two sources, two different questions

SourceHome valueMonthly rent
Zillow market index$336.6K$1.7K
ACS occupied housing$362.2K$1.4K
Zillow measures current market indexes. ACS reports surveyed owner value and gross rent for occupied housing. The rows are context, not interchangeable estimates.
Direct local rental evidence

Recent leases and rental-market liquidity in Minneapolis, MN

These Apartment List observations match the exact city Census code 2743000. They are kept separate from Zillow asking rent, Census occupied-home rent and wider metro measures.

Direct recent-lease rent history

Monthly overall-rent index; missing observations are not filled from another geography.

$1,462$1,399$1,3362021-082026-07
Recent-lease rent$1,4622026-07 · +2.3% year over year
Rental vacancy9.1%2026-07 · +0.2 percentage points year over year
Time on market31 days2026-07 · -1.3 days year over year
Direct city depth

Households and housing form behind the medians

Median household income$81k

Annual ACS household measure.

Rent-to-income screen25.0%

Annual ZORI divided by ACS median income.

ACS rent burden48.1%

Renters paying at least 30% of household income toward gross rent.

Average household size2.12

People per occupied housing unit.

Single-family stock43.8%

Detached and attached one-unit structures.

Large multifamily stock33.6%

Housing in structures with 20 or more units.

Vacant and for rent45.1%

Share of vacant units listed by ACS as for rent, not a market vacancy rate.

Unemployment5.9%

Share of the civilian labor force.

Poverty16.0%

ACS population for whom poverty status is determined.

These are citywide context measures. They cannot tell you the rent, vacancy, expenses or tenant demand for a particular neighborhood or property.
ZIP rental landscape

How asking rent and renter pressure vary inside Minneapolis

This view uses 12 direct Zillow ZIP markets matched to Census ZCTAs. It is a selected evidence set, not a neighborhood ranking or an exhaustive city inventory.

Selected ZIP range$1,393–$2,014Zillow asking-rent index
Monthly spread$621highest minus lowest selected ZIP
Observed burden range32.7%–62.2%ACS renter households paying 30%+
Renter households covered85,248across the selected ZCTAs
01 · ASKING RENT LADDERDirect ZIP ZORI
Horizontal bars compare Zillow asking-rent indexes across the selected direct-evidence ZIP set.55401$2,01455413$1,80955412$1,77355411$1,75855418$1,70955414$1,52955408$1,51955407$1,48255403$1,45155404$1,43855406$1,43655405$1,393
02 · PRESSURE MATRIXRent × observed burden
Each point is one selected ZIP and ZCTA match. Horizontal position is Zillow asking rent and vertical position is the ACS renter cost-burden share.64.7%56.1%47.5%38.8%30.2%554085541455404554035540155407554065540555413554185541155412Zillow asking-rent index →ACS burden share →
03 · BENCHMARK GAPZORI vs HUD 2BR
Bars show the percentage difference between the Zillow blended asking-rent index and the local HUD two-bedroom standard. Their housing universes differ.55401+117.8%55413+105.9%55412+103.7%55411+102.9%55418+100.0%55414+89.5%55408+88.9%55407+86.7%55403+84.9%55404+84.1%55406+84.0%55405+81.5%
WHAT THE LOCAL DISTRIBUTION SAYS

Within Minneapolis, the selected direct-evidence set contains 12 ZIP/ZCTA matches, ordered by renter households, covering 85,248 renter households; 17 ZIPs were eligible, so this is a sizeable but nonexhaustive decision set rather than a full inventory. Zillow’s June 2026 ZORI, a typical observed asking-rent index, ranges from $1,393 to $2,014 across the displayed areas—a $621 spread—with a $1,524 median. The practical question is therefore not simply which area is lowest on the index, but whether the live units, lease costs, and bedroom needs that a household is shopping can be found at the relevant point in that spread.

Three measures answer different questions. The ACS 2024 five-year ZCTA median gross-rent estimates run from $1,082 to $2,023, while HUD’s FY2026 two-bedroom FMR/SAFMR standard is $1,709 for every displayed area. Those are not substitutes for ZORI asking rent: in 55405, the $1,393 ZORI is 81.5% of the HUD two-bedroom standard; in 55401, $2,014 is 117.8%. Gross rent records a survey measure for existing occupants, ZORI tracks typical asking-rent conditions, and HUD is an administrative benchmark by bedroom. Read their gaps as a prompt to inspect unit type and price composition, not as a conversion between sources.

ACS burden and vacancy estimates add a separate trade-off screen. The share of renter households paying 30% or more of income for rent spans 32.7% to 62.2% in the displayed ZCTAs, versus 48.1% for the city; ACS vacancy ranges from 5.2% to 12.0%, versus 7.8% citywide. 55404 illustrates why the signals should not be collapsed: its $1,438 ZORI is near the low end, yet its burden estimate is 51.7% and vacancy estimate is 12.0%. This observed combination does not show why either measure is high or low, and vacancy is not a live count of rentable listings. A household’s income, unit size, and total lease payment remain the decision variables.

Important limits remain. ZCTA boundaries are statistical and do not exactly match USPS delivery ZIPs, while the evidence set pairs geographic matches rather than producing a neighborhood inventory. The Zillow observation, ACS figures, and HUD standard have different release windows and construction, preventing a single market-rent conclusion. Before acting, verify the address, current advertised rent, bedroom count, utilities and other mandatory charges, availability, concession terms, lease length, and income-screening rules for the specific property. Use the published figures only as area-level context and recalculate the household budget from the actual offer.

Selected ZIP evidence

Keep each source universe visible

17 ZIP profiles passed the city gate; the 12 with the most renter households are shown.

ZIP / ZCTAZillow asking rentACS gross rentHUD 2BRBurden 30%+VacancyIncome screen
55408$1,519$1,364$1,70941.1%5.9%$61k
55414$1,529$1,425$1,70956.6%11.2%$61k
55404$1,438$1,082$1,70951.7%12.0%$58k
55403$1,451$1,241$1,70948.9%11.1%$58k
55401$2,014$2,023$1,70934.8%9.1%$81k
55407$1,482$1,291$1,70953.1%8.0%$59k
55406$1,436$1,281$1,70941.9%5.2%$57k
55405$1,393$1,231$1,70940.9%9.4%$56k
55413$1,809$1,605$1,70932.7%8.3%$72k
55418$1,709$1,425$1,70939.6%6.7%$68k
55411$1,758$1,226$1,70962.2%10.6%$70k
55412$1,773$1,401$1,70957.1%6.6%$71k
READ BEFORE USING

The direct-evidence selection includes 12 of 17 eligible ZIP/ZCTA matches, ordered by renter households. It is not an exhaustive inventory, and ZCTAs are Census statistical areas rather than exact equivalents to USPS delivery ZIP boundaries.

Zillow’s ZIP index, ACS five-year ZCTA estimates, and HUD FMR/SAFMR standards differ in release period, geography, and underlying concept. They cannot be averaged, treated as interchangeable, or used to determine the rent, eligibility, or affordability of any particular apartment.

SOURCE LEDGERCensus ACS five-year — ZCTA housing and incomeACS 2024 5-year ZCTA · pulled 2026-08-08HUD USPS crosswalk and Small Area FMRs — ZIP rent fallbackZIP-CBSA 2025Q4 + SAFMR FY2026 · pulled 2026-07-26Zillow ZORI — ZIP market rentsZORI ZIP 2026-06 · pulled 2026-08-08
Curated city comparisons

Minneapolis in direct city-to-city decisions

Each comparison keeps both records inside city limits and opens only when the pair differs materially on multiple decision signals.

Browse all city comparisons →
Closest market alternatives

Three useful contrasts, not a synthetic winner

The peer set broadens the decision without mixing geographies. Price, rent and housing characteristics remain city-level for every place.

Comparable market profile

Entry price, rent and gross yield

Minneapolis, MNRochester, MNDuluth, MNArlington, TX
Typical home valueZillow ZHVIMinneapolis$336.6KRochester$348.3KDuluth$303.6KArlington$314.4KObserved market rentZillow ZORI / monthMinneapolis$1.7KRochester$1.7KDuluth$1.5KArlington$1.5KGross yieldZORI × 12 ÷ ZHVIMinneapolis6.0%Rochester5.9%Duluth5.8%Arlington5.9%
Bars begin at zero within each measure. Gross yield is a screening ratio before financing, taxes, insurance, vacancy, maintenance or management costs.
Same state01

Rochester, MN

Compared with Minneapolis, typical home value is $12k higher, monthly rent is $16 higher, and gross yield is 0.1 percentage points lower.

Rent burden 30%+
48.0%
Renter share
34.9%
One-unit stock
67.4%
20+ unit stock
17.6%
Same state02

Duluth, MN

Compared with Minneapolis, typical home value is $33k lower, monthly rent is $228 lower, and gross yield is 0.2 percentage points lower.

Rent burden 30%+
54.0%
Renter share
40.6%
One-unit stock
62.3%
20+ unit stock
15.5%
Closest data profile03

Arlington, TX

Compared with Minneapolis, typical home value is $22k lower, monthly rent is $140 lower, and gross yield is 0.1 percentage points lower.

Rent burden 30%+
59.6%
Renter share
45.7%
One-unit stock
66.1%
20+ unit stock
9.1%

These are analytical alternatives, not recommendations. The structural measures come from Census ACS; price and rent use the Zillow releases shown on each card and in the source ledger below.

Wider market context

What surrounds the city without being mistaken for it

The layers below answer different questions. County records describe listing, migration, financing and hazard conditions around the city; metro records describe jobs, supply and permits; the mortgage rate is national.

Same measure, wider boundary

City marker against intersecting counties

CityCounty range
Typical home value$395.9K$395.9K$336.6KObserved market rent$1.8K$1.8K$1.7K
Both levels use Zillow indexes, but the county records cover land and housing outside the city. The comparison supplies context; it does not replace the city value.
Same Zillow index families

City limits versus the linked metro

MinneapolisMetro
Observed market rentMetro $1.7KCity $1.7K · -2.4%Typical home valueMetro $395.7KCity $336.6K · -14.9%Gross yieldMetro 5.2%City 6.0% · +14.7%
Zillow ZORI and ZHVI use the same release month at both boundaries. Gross yield is rent × 12 ÷ home value; the metro contains the city and is context, not a substitute.

Search all direct city–metro gaps in the interactive atlas.

COUNTY LAYER

The intersecting county

This boundary extends beyond the city and is shown only as context.

2026-06
Active listings
3,108
Listing DOM
37 days
FHFA one-year
▲ 3.0%
Net migration
-2,068
Investor share
8.1%
Effective property tax
1.14%
Top hazard
inland flooding
Expected loss ratio
0.10%
METRO LAYER

Minneapolis, MN

Open metro analysis →
Job growth▲ 0.2%12m to 2026-06
Permitted units13,9062026 YTD through M06
Permits / 1,0003.7broader metro population
Months of supply2.02026-05-01
Median DOM22 daysRedfin metro tracker
Price drops33.8%Redfin metro tracker
Wider-context figures are not inputs to the city gross yield and are never used to fill a missing city price, rent or ACS measure.
What can break the thesis

Three checks before using the city averages

  1. 01

    Gross yield excludes operating costs, financing, vacancy and capital spending.

  2. 02

    City rent burden, poverty and unemployment may constrain affordability but do not predict any tenant’s performance.

  3. 03

    County, metro and national context may not match city or property-level outcomes.

Questions answered

Quick reading guide

Can the ACS and Zillow housing measures be combined?

No. They differ in concept, coverage and period; ACS gross rent also includes selected utilities.

Does the city vacancy rate prove that a rental will lease quickly?

No. It is citywide housing-stock context, not a property-specific absorption measure.

What is needed beyond the gross-yield screen?

Property-level rent evidence, condition, taxes, insurance, operating expenses, reserves and actual financing terms.

Sources and geography

What belongs to this city page

Census recognizes this as Minneapolis city. The place intersects Hennepin County.